Medicare Part C Benefits Consumers Should Compare
Compare Medicare Part C benefits side by side to find the right plan. Call (510)-663-7016 for expert guidance on your options.
By Zara Voss
Choosing a Medicare Advantage plan can feel like comparing apples to oranges when every plan advertises a slightly different basket of benefits. Medicare Part C, also known as Medicare Advantage, bundles hospital and medical coverage with often extra services like dental, vision, and fitness memberships. But not all Part C plans are created equal, and the benefits that matter most depend on your health needs and budget. This guide breaks down the specific medicare part c benefits consumers should compare before enrolling, so you can spot the real differences and avoid paying for extras you do not need or missing coverage you do.
The Core Benefits Every Medicare Advantage Plan Must Provide
Every Medicare Advantage plan must cover everything Original Medicare (Part A and Part B) covers, with one exception: hospice care, which remains under Part A. That means hospital stays, doctor visits, outpatient care, preventive services, and emergency care are all included. However, the cost-sharing structure can vary widely. One plan might charge a $0 copay for primary care visits, while another charges $25. Comparing these core benefits is the first step because they affect your out-of-pocket costs for routine care.
Another critical core benefit to examine is the annual out-of-pocket maximum. Unlike Original Medicare, which has no cap on out-of-pocket spending, Medicare Advantage plans limit your financial exposure. In 2026, the maximum out-of-pocket limit for in-network care is $9,250, but many plans set lower limits. A plan with a $4,000 cap could save you thousands if you have a major health event. Consumers should compare this figure closely, especially if they have ongoing health conditions.
Emergency and urgent care coverage is also standardized but worth verifying. All Part C plans must cover emergency care anywhere in the U.S. and worldwide, with a maximum copay of $120 for emergency department visits. Urgent care copays can differ, so check those as well. These core benefits form the foundation, but the real differentiation often lies in the optional extras.
Optional Extras: Dental, Vision, and Fitness Benefits
Dental, vision, and hearing coverage are among the most compared benefits because Original Medicare offers limited coverage for these services. Medicare Advantage plans often include routine dental exams, cleanings, and even dentures, but the annual maximum benefit can range from $500 to $3,000 or more. Some plans cover only preventive services, while others include comprehensive care like crowns and root canals. Consumers should compare not just whether dental is included, but what the annual cap is and whether major services are covered after a waiting period.
Vision benefits typically cover annual eye exams and an allowance for glasses or contacts. The allowance can vary from $100 to $300 per year. If you have specific vision needs, such as cataract surgery or specialty lenses, check whether the plan's vision network includes your preferred providers. Hearing aid coverage is another differentiator; some plans offer a fixed allowance toward hearing aids, while others provide discounted pricing through a network.
Fitness benefits have become a popular perk. Many plans include a gym membership through programs like SilverSneakers or Renew Active, which offer access to thousands of fitness locations and online classes. If you value staying active, compare which fitness network each plan uses and whether it includes classes or personal training. These extras can add real value, but only if you will use them. A plan with a rich fitness benefit but a higher premium might not be worth it if you prefer to exercise at home.
How Drug Coverage Is Bundled into Part C Plans
Most Medicare Advantage plans include prescription drug coverage (Part D) as part of the package. This is a major convenience, but the drug benefit design varies significantly. Each plan has its own formulary, a list of covered drugs, and tier structure. A drug you take could be on a low tier with a $10 copay in one plan and a higher tier with a $47 copay in another. Consumers should compare their specific medications across plans using the Medicare Plan Finder tool or by checking each plan's formulary.
Beyond copays, look at the deductible and the coverage gap (donut hole). In 2026, the maximum deductible for Part D is $615, but some plans waive it for certain tiers. The coverage gap has been largely eliminated for brand-name drugs, but you still need to understand how your plan phases in coverage. Also, check whether the plan requires prior authorization or step therapy for your drugs, which can delay access. If you take multiple medications, the drug coverage comparison alone could save you hundreds of dollars per year.
Some Medicare Advantage plans do not include drug coverage (these are called MA-only plans). If you choose one, you will need to enroll in a standalone Part D plan, which adds another premium. For most consumers, a plan with built-in drug coverage simplifies things, but it is essential to verify that your pharmacy is in the plan's network and that the drugs you need are covered at a reasonable cost.
Comparing Provider Networks and Referral Rules
Medicare Advantage plans often use HMO or PPO networks, and the rules for seeing specialists differ. HMO plans typically require you to use in-network providers and get a referral from your primary care doctor to see a specialist. PPO plans allow you to see out-of-network providers but at a higher cost. If you have established relationships with doctors or specialists, compare whether they are in each plan's network. A plan that saves you $20 per month in premiums is not a good deal if it means losing access to your cardiologist.
Also, consider the prior authorization requirements. Some plans require pre-approval for certain services, such as elective surgeries or advanced imaging. While this is a common cost-control measure, it can create delays. Consumers should review the plan's prior authorization list and consider how it might affect their care. If you have a chronic condition or anticipate needing specialized care, a plan with fewer restrictions may be worth a higher premium.
For agents helping clients navigate these choices, understanding network adequacy is crucial. MedicareLeads.com provides educational resources and leads for agents who want to help consumers find plans that match their provider preferences. If you are an agent looking to grow your Medicare business, consider how you can guide clients through these comparisons to build trust and close more sales.
Cost-Sharing and Premium Comparisons
Premiums for Medicare Advantage plans vary by plan and location. Some plans have $0 monthly premiums, while others charge $50 or more. However, a low premium does not always mean lower overall costs. You must compare the copays for services you use frequently, such as specialist visits, lab work, and imaging. For example, a plan with a $0 premium might charge $50 for a specialist visit, while a plan with a $30 premium charges $20. If you see specialists often, the higher premium plan could be cheaper overall.
Also, consider the cost of hospitalization. Part C plans typically charge a daily copay for hospital stays, such as $250 per day for days 1-5, and then $0 per day for the rest of the stay. Some plans have a copay for each day of the stay, while others have a tiered structure. Compare these costs carefully, especially if you have planned surgeries or a history of hospitalizations. The annual out-of-pocket maximum is your safety net, but the path to reaching it matters.
Consumers should also factor in the Part B premium, which everyone pays regardless of whether they choose Original Medicare or Medicare Advantage. In 2026, the standard Part B premium is $185.00 per month. Some Medicare Advantage plans offer a give-back benefit that reduces your Part B premium, but these plans may have higher copays elsewhere. Compare the total cost of care, not just the premium.
Checklist for Comparing Benefits Side by Side
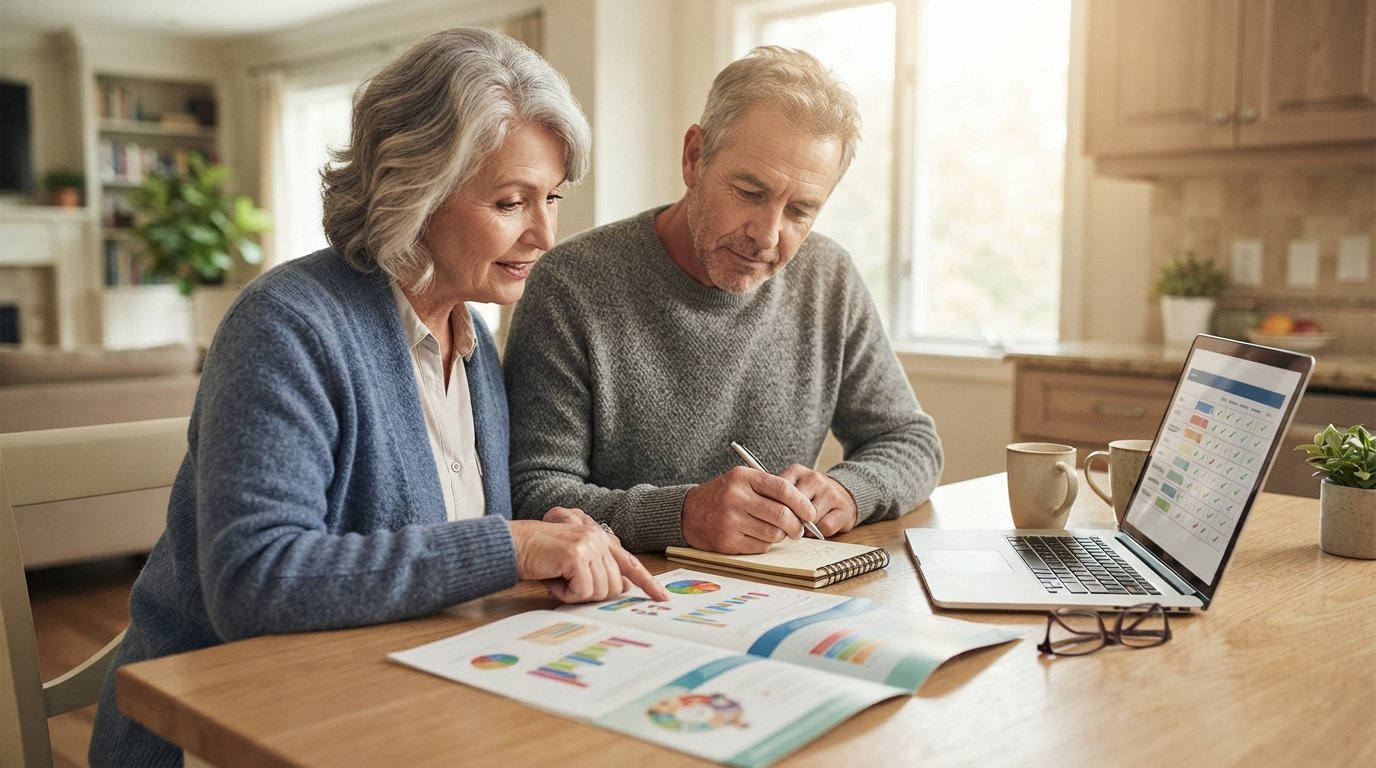
To make an informed decision, consumers should create a comparison chart or use a worksheet to evaluate each plan. Start by listing the plans available in your ZIP code, then gather the Summary of Benefits and Evidence of Coverage documents. These documents outline the core benefits, extras, and cost-sharing details. Here is a checklist of the key items to compare:
- Monthly premium: The amount you pay each month for the plan.
- Annual out-of-pocket maximum: The most you will pay for in-network care before the plan covers 100%.
- Primary care and specialist copays: The cost per visit.
- Hospital stay copays: The daily cost for inpatient care.
- Drug coverage: Formulary tiers, copays, and prior authorization rules for your medications.
- Dental, vision, and hearing benefits: Annual maximums, covered services, and network restrictions.
- Fitness program: Which network is used and what it includes.
- Provider network: Whether your doctors and hospitals are in-network.
- Referral requirements: Whether you need a referral to see a specialist.
- Extra benefits: Transportation, telehealth, over-the-counter allowances, and meal delivery.
After listing these details, rank the benefits by importance to your health and budget. For example, if you take expensive medications, drug coverage might be the top priority. If you travel frequently, a PPO plan with out-of-network coverage could be more valuable than an HMO with a lower premium. This structured comparison helps you see beyond marketing materials and focus on the actual value each plan delivers.
For agents, offering this checklist to clients can streamline the enrollment process and reduce post-sale surprises. MedicareLeads.com provides tools and exclusive leads for agents who want to help consumers make these comparisons efficiently. By guiding clients through a side-by-side analysis, agents can demonstrate expertise and build long-term relationships.
Special Benefits: Transportation, Telehealth, and Over-the-Counter Allowances
Many Medicare Advantage plans now include transportation benefits for medical appointments, often limited to a certain number of trips per year. This can be a lifesaver for consumers who no longer drive or live in rural areas. Compare the number of trips allowed, the distance limit, and whether the service must be scheduled in advance. Telehealth benefits have also expanded, with many plans offering $0 copays for virtual visits with primary care doctors or specialists. If you are comfortable with technology, this can save time and money.
Over-the-counter (OTC) allowances are another popular extra. These provide a quarterly or monthly credit to purchase items like vitamins, pain relievers, and first-aid supplies from a catalog or participating pharmacy. The allowance amount can range from $25 to $100 per quarter. While these benefits are nice to have, they should not drive your plan choice unless you regularly use OTC products. Focus on the benefits that impact your health and financial security first.
Some plans also offer meal delivery after a hospital stay, caregiver support, and acupuncture. These niche benefits can be valuable for specific populations, but they are not universal. Read the fine print to understand eligibility and limits. For example, meal delivery might be limited to 14 days after discharge and require a referral. If you have a caregiver or expect to need post-hospital support, check whether the plan includes these services.
How to Use Medicare Plan Finder and Agent Resources
The Centers for Medicare and Medicaid Services (CMS) provides the Medicare Plan Finder tool at Medicare.gov, which allows you to compare plans side by side based on your medications and providers. You can enter your ZIP code, list your drugs, and select your pharmacies to see estimated annual costs. The tool also shows plan star ratings, which reflect quality and member satisfaction. Consumers should use this tool as a starting point, then verify details with the plan directly or through a licensed agent.
Licensed agents can offer personalized guidance and help you understand the nuances of each plan. If you are an agent, you can leverage resources from MedicareLeads.com to stay informed about plan changes and to connect with consumers who are actively seeking help. The platform offers exclusive and shared leads, inbound calls, and live transfers, giving agents flexible options to grow their business while helping consumers navigate Medicare Advantage benefits.
For legal professionals and businesses seeking to reach consumers in need of legal services, AttorneyLeads provides a parallel model of pre-screened, exclusive leads. Just as MedicareLeads.com connects agents with Medicare shoppers, AttorneyLeads connects attorneys with clients in practice areas like DUI, personal injury, and bankruptcy. This cross-industry comparison highlights the value of specialized lead generation in regulated markets.
When comparing plans, always verify that the doctors and hospitals you want are in the network, and confirm that your drugs are on the formulary. If you have questions, call the plan's member services or work with an agent who can explain the differences. Remember that Medicare Advantage plans can change their benefits and costs each year, so review your options during the annual enrollment period (October 15 to December 7) or during a special enrollment period if you qualify.
Understanding the Medicare Part A coverage for surgeon fees can also inform your comparison, since Part C plans must cover these services and may have different cost-sharing rules. Knowing the underlying Part A benefits helps you spot when a Part C plan is offering a genuine extra versus simply repackaging standard coverage.
Making the Final Decision
After comparing core benefits, optional extras, drug coverage, networks, and costs, you should have a short list of two or three plans that meet your needs. Consider the plan's star rating, which ranges from 1 to 5 stars, with 5 being the highest. Plans with 4 or more stars often have better customer service and care coordination. Also, think about the plan's reputation in your community and whether it has a robust provider network in your area.
It is also wise to consider future health needs. If you are relatively healthy now but anticipate needing more care as you age, a plan with a lower out-of-pocket maximum and comprehensive extras might be worth a higher premium. Conversely, if you are on a tight budget and rarely see doctors, a lower-premium plan with basic coverage could suffice. There is no one-size-fits-all answer; the best plan is the one that aligns with your health and financial situation.
Finally, do not overlook the importance of customer service. A plan that is easy to reach and resolves issues quickly can save you frustration. Read reviews and ask friends or family about their experiences. If you work with an agent, ask about their experience with the plan's administrative processes. A knowledgeable agent can help you avoid common pitfalls and ensure a smooth transition.
In summary, the medicare part c benefits consumers should compare go beyond the premium. By systematically evaluating core coverage, extras, drug benefits, networks, and costs, you can choose a plan that provides real value and peace of mind. Take advantage of available tools and professional guidance to make an informed decision that supports your health and budget for the year ahead.