Medicare Client Retention Strategies for Agents
Master medicare client retention strategies for agents to keep your book stable and profitable. Call 5106637016 for expert help.
By Ronan Steele
Acquiring a new Medicare client costs significantly more than keeping an existing one. Yet many agents pour the majority of their budget into lead generation while treating retention as an afterthought. The result is a revolving door: seniors enroll, drift away during the next Annual Enrollment Period, and the agent starts from scratch each fall. In a market where trust drives every renewal decision, retention is not a luxury. It is the foundation of a sustainable book of business.
The agents who thrive year after year understand that Medicare client retention strategies for agents are not about gimmicks or aggressive upselling. They are about systematic follow-up, proactive communication, and positioning yourself as the trusted advisor a senior can call when a plan changes, a pharmacy bill spikes, or a doctor leaves a network. When you get retention right, your clients become your best lead source, and your business compounds instead of resetting every January.
This article breaks down the most effective retention tactics for Medicare agents, from onboarding sequences to annual review frameworks, and shows how to build a book of business that stays loyal for a decade or more.
Why Retention Matters More Than Ever for Medicare Agents
The Medicare market is becoming more crowded each year. Carriers expand their product lines, online comparison tools make it easier for seniors to shop on their own, and call centers flood mailboxes with promises of extra benefits. In that environment, loyalty is fragile. A client who feels ignored during the year is far more likely to take a call from a competing agent during AEP.
Retention protects three things at once: revenue, reputation, and referral flow. A retained client generates renewal commissions year after year without additional acquisition costs. That same client is also far more likely to refer a spouse, a neighbor, or a friend from church. Referrals from existing clients close at dramatically higher rates than cold leads because trust transfers almost instantly.
Retention also reduces your dependency on purchased leads. If you are buying leads every fall to replace churn, your margins shrink. If your book is stable, you can invest more selectively and even use resources like a licensed insurance lead marketplace to fill specific gaps rather than replacing your entire client base.
The math is simple. If you retain 90 percent of your book instead of 70 percent, you keep hundreds of commissionable members who cost you nothing extra to acquire. Over five years, that difference compounds into a dramatically larger, more profitable business.
Build a Strong Onboarding Experience That Sets the Tone
Retention starts on day one, not during the next enrollment period. The first two weeks after a client enrolls shape how they view you for the entire relationship. If they hear from you once at enrollment and then nothing until October, they will assume you are only interested in the sale. If they hear from you multiple times with helpful, non-sales touches, they will see you as a resource.
A strong onboarding sequence includes a welcome call, a confirmation of what they enrolled in, a summary of what to expect regarding their card, premium, and coverage start date, and a clear way to reach you. It also includes setting expectations about when you will check in next.
Here is a simple onboarding checklist that high-retention agents use consistently:
- Welcome call within 48 hours of enrollment confirmation.
- Written summary of plan details, premium, and effective date sent by mail or email.
- Reminder about when the member ID card will arrive and what to do if it does not.
- Introduction to your client portal or preferred contact method.
- Scheduled check-in for 30 to 60 days after the plan takes effect.
That 30 to 60 day check-in is especially important. It catches problems early, such as a pharmacy that does not have the client in the system, a doctor who turns out to be out of network, or confusion about copays. Solving those issues quickly builds enormous goodwill. A client who sees you fix a problem in week three will trust you for years.
Create a Year-Round Communication Rhythm
Most agents communicate with clients only during AEP. That is a mistake. The agents with the highest retention rates touch their book multiple times per year with content that has nothing to do with selling. These touches keep you top of mind and give clients a reason to stay.
A workable rhythm looks like this: a quarterly newsletter or email with plan reminders, a mid-year check-in call or text, a pre-AEP review invitation in early fall, and a post-AEP thank-you or confirmation. Add birthday and holiday greetings if they fit your style, but keep them genuine rather than automated-sounding.
For clients who prefer phone calls, a brief mid-year call works better than email. Ask two questions: how are your prescriptions working out, and have you had any issues with doctors or hospitals. Those two questions surface most problems before they become reasons to switch.
Communication should also be documented. Use a simple CRM or spreadsheet to log every touch, note any concerns, and set reminders for follow-up. The more organized your records, the easier it is to personalize each interaction and avoid embarrassing gaps.
Master the Annual Review Conversation
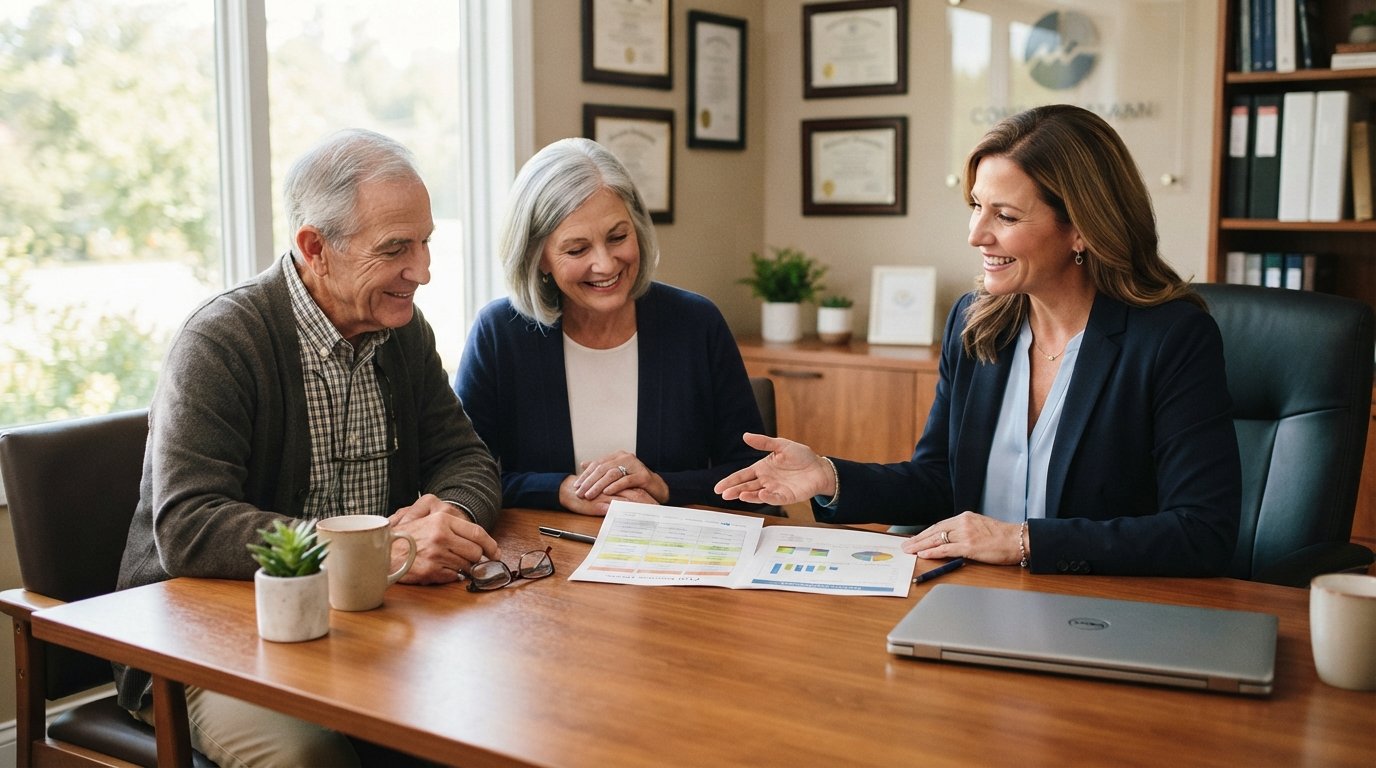
The annual review is the single most important retention event of the year. It is your chance to confirm the client is still in the right plan, address any changes in their health or prescriptions, and reinforce your value. Agents who skip annual reviews lose clients to competitors who do not.
Schedule reviews before AEP begins, ideally in September or early October. Send a clear invitation explaining that plan formularies, networks, and premiums change every year, and that you want to make sure their current plan still fits. That framing positions the review as a service, not a sales pitch.
During the review, walk through a structured checklist:
- Confirm current medications, dosages, and pharmacies.
- Review any new diagnoses or provider changes.
- Compare the current plan against at least two alternatives.
- Explain any premium, deductible, or formulary changes.
- Document the decision and schedule the next check-in.
Even if the client stays in the same plan, the review reinforces that you are watching their back. That alone reduces churn. If a change is needed, you have positioned yourself as the agent who caught it first, not the one who let a problem slide.
Personalize Every Interaction at Scale
Seniors value being known. A generic mailer that says "Dear Medicare Member" does not build loyalty. A handwritten note that references a client's grandchild, hobby, or recent surgery does. Personalization does not require enormous effort, but it does require a system.
Keep notes on non-medical details: a client's birthday, spouse's name, favorite team, or the fact that they volunteer at a local food bank. Reference those details in calls and cards. When a client feels like a person rather than a policy number, they are far less likely to shop around.
Personalization also applies to problem-solving. If a client calls about a denied claim, do not just explain the appeal process. Walk them through it, follow up to confirm the claim was resolved, and check back a week later. That level of service is rare and memorable.
For agents managing larger books, technology can help. A CRM with reminder tasks, call logging, and templates lets you personalize at scale without dropping balls. The goal is not automation for its own sake but consistency, so no client falls through the cracks.
Turn Retention Into Referrals and Growth
Retention and referral generation are two sides of the same coin. A happy client is the most cost-effective lead source you have. But referrals do not happen automatically. You have to ask, and you have to make it easy.
After a successful annual review or a resolved issue, ask a simple question: "Do you know anyone else who might need help understanding their Medicare options?" That question is low-pressure and natural. Most clients will think of someone, even if they do not refer immediately.
You can also create referral incentives where compliance allows, such as a small gift card or charitable donation in the client's name. Always check carrier and CMS rules before offering anything of value. In many cases, a sincere thank-you note is enough.
Referrals also flow from visibility. Stay active in senior centers, churches, and community events. Host educational workshops that are purely informational. When clients see you as a community resource rather than a salesperson, they refer more often and stay longer.
For agents who need to supplement referrals with purchased leads, tools like Medicare lead bundling and pricing strategies can help you allocate budget efficiently while keeping retention as the core of your growth model.
Use Technology and Data to Reduce Churn
Retention improves when you can see problems coming. Data and simple technology tools help you spot at-risk clients before they leave. For example, if a client misses a premium payment, changes pharmacies, or stops responding to calls, those are warning signs.
Set up alerts in your CRM for missed payments, plan changes, or gaps in communication. A quick call after a missed payment can save a client from losing coverage and strengthen the relationship. Similarly, if a client's plan is being discontinued or significantly changed, reach out before they hear it from the carrier.
Analytics can also help you understand which client segments churn most. Maybe clients who enrolled during a specific period, or who live in a certain ZIP code, are more likely to leave. Once you identify the pattern, you can adjust your onboarding or communication for that group.
Technology should support human relationships, not replace them. A well-timed text reminder about an annual review is helpful. A barrage of automated emails is not. Use data to inform your outreach, but keep the conversation personal.
Handle Objections and Concerns Before They Become Cancellations
Most clients do not leave because they found a better plan. They leave because they felt ignored, confused, or misled. Addressing concerns early prevents small frustrations from turning into cancellations.
When a client expresses dissatisfaction, listen fully before responding. Repeat back what you heard to confirm understanding. Then offer a clear next step, whether that is a plan comparison, a call to the carrier, or a simple explanation of how something works. Follow up to confirm the issue was resolved.
If a client is considering a different plan, do not panic or pressure them. Ask what is driving the interest. Sometimes a competitor is promising benefits that do not actually exist, or the client misunderstood something. A calm, factual conversation often saves the relationship.
If the client does decide to leave, part on good terms. Send a thank-you note and let them know you are still available if they have questions. Many clients who leave eventually come back, especially if their new agent disappears after the sale.
Measure What Matters and Improve Continuously
You cannot improve retention without measuring it. Track your annual retention rate, the number of clients who switch plans, and the reasons they give for leaving. Review these numbers quarterly, not just after AEP.
Set a target retention rate and work backward to the behaviors that drive it. If your goal is 90 percent retention, you likely need at least three meaningful touches per client per year, a completed annual review for every client, and a process for resolving issues within 48 hours.
Ask clients for feedback directly. A short survey or a few questions during the annual review can reveal gaps you did not know existed. When clients see you acting on their feedback, trust deepens.
Finally, celebrate retention wins. When a client stays for five years or refers a family member, acknowledge it. Retention is a long game, and the agents who treat it that way build books that are stable, profitable, and deeply rewarding.
The most successful Medicare agents do not just sell plans. They build relationships that last through health changes, plan changes, and everything else that comes with aging. By focusing on onboarding, communication, annual reviews, personalization, and continuous improvement, you can turn retention from a vague hope into a measurable competitive advantage.