Medicare Application Process Step by Step for New Beneficiaries
Get a clear Medicare application process step by step for new beneficiaries, from Social Security to active coverage. Call (510)-663-7016 for guidance.
By Lyra Vale
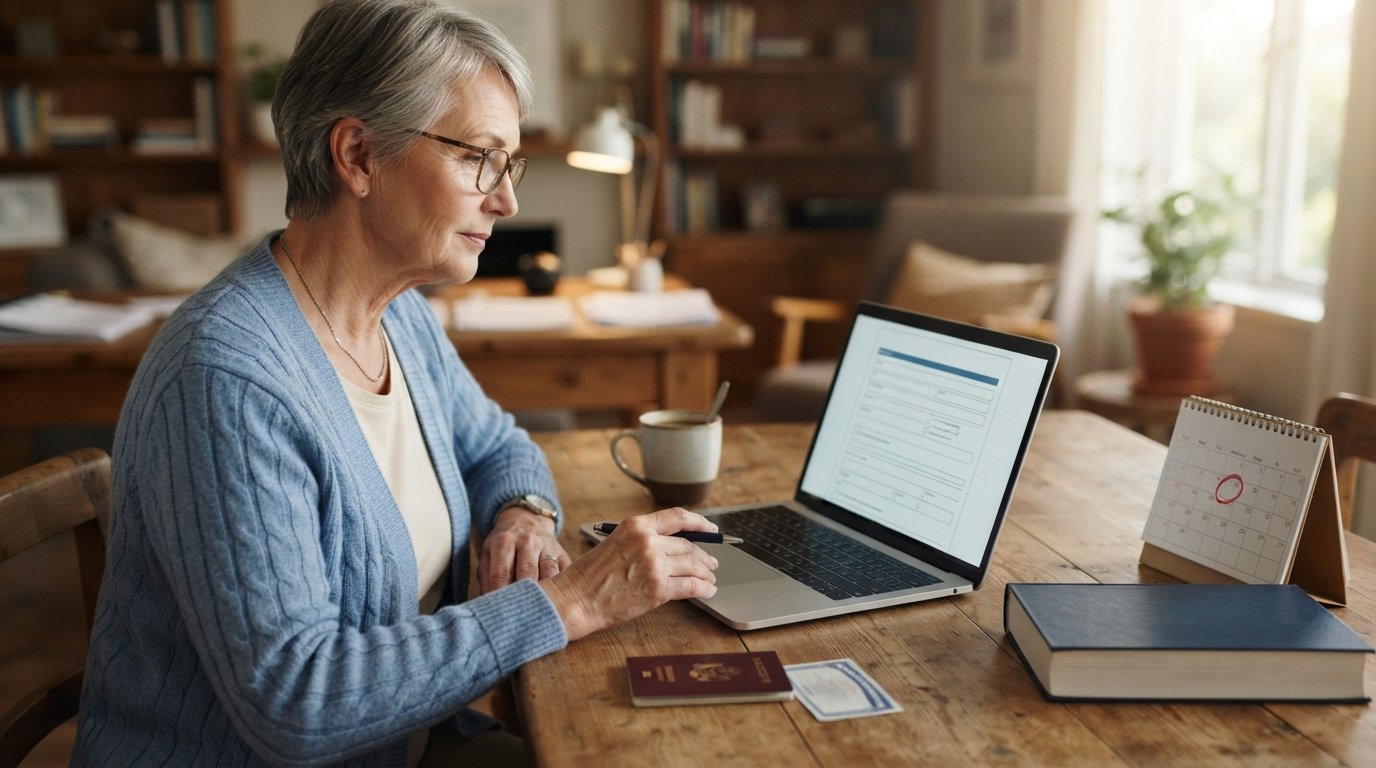
Turning 65 is a milestone, but it comes with a deadline that can cost you money if you miss it. The Medicare application process step by step for new beneficiaries is not complicated, but it is unforgiving: sign up late and you may face permanent premium penalties. This guide walks you through each stage, from your first submission to Social Security to the day your card arrives and your coverage goes live. Whether you are still working, already collecting Social Security, or helping a parent enroll, the sequence below will keep you on track.
Start With Social Security: Your Entry Point for Part A and Part B
Almost every Medicare enrollment begins with the Social Security Administration, not with Medicare itself. Original Medicare has two core pieces: Part A covers hospital stays, skilled nursing, and some home health care, while Part B covers doctor visits, outpatient care, and preventive services. You apply for both through Social Security, either online, by phone, or in person at a local office.
The fastest route is the online application at ssa.gov. You will need your Social Security number, proof of age and citizenship (or lawful presence), and information about any current employer coverage. The form takes about 10 to 30 minutes to complete. If you prefer, you can call 1-800-772-1213 to enroll by phone, or schedule a visit to a local office. Paper forms are also accepted but add processing time.
Here is the general sequence new beneficiaries follow:
- Confirm your Initial Enrollment Period, which is the seven-month window around your 65th birthday.
- Gather your identification documents and employer coverage details.
- Submit your Part A and Part B application through Social Security.
- Receive your Medicare card and review the effective date printed on it.
- Decide whether to add Part D, Medicare Advantage, or a Medigap policy.
Each step feeds the next. If you skip the first one and assume you have more time than you do, the rest of the process can unravel. Mark your window on a calendar the day you read this.
When Automatic Enrollment Applies and When It Does Not
Some people never fill out an application at all. If you are already receiving Social Security retirement benefits or Railroad Retirement Board benefits before you turn 65, you are automatically enrolled in Part A and Part B. Your Medicare card arrives in the mail roughly three months before your birthday month, and coverage starts on the first day of your birthday month.
Automatic enrollment does not apply to everyone, though. You must apply yourself if any of these situations describe you:
- You are not yet collecting Social Security benefits.
- You have delayed retirement benefits past 65.
- You are under 65 and qualify through disability or ALS (Lou Gehrig's disease).
- You have end-stage renal disease and meet specific criteria.
If you fall into the second group, the burden is on you to file during your Initial Enrollment Period. That window opens three months before your 65th birthday month, includes your birthday month, and closes three months after. Enrolling in the first three months generally gives you coverage on the first day of your birthday month. Enrolling later in the window can delay your start date by one to three months.
One more wrinkle: even if you are automatically enrolled in Part A, you can decline Part B if you have employer coverage through active employment. That decision has long-term consequences, so review it carefully with a licensed agent before you opt out. For individuals who face unique documentation situations, such as lacking a standard Social Security number, a detailed walkthrough of applying for Medicare without a Social Security number can clarify the alternative pathways.
Choosing Between Original Medicare and Medicare Advantage
Once your Part A and Part B enrollment is confirmed, you face the biggest fork in the road: how you receive your benefits. Original Medicare lets you see any provider nationwide who accepts Medicare, and you can add a Medigap supplement to cover most out-of-pocket costs and a Part D plan for prescriptions. Medicare Advantage, also called Part C, replaces the way you receive Original Medicare benefits with a private plan that often bundles drug coverage and extras like dental or vision.
Neither path is universally better. Your choice depends on your doctors, your prescriptions, your travel habits, and your budget. Original Medicare plus Medigap typically means higher monthly premiums but predictable costs and total provider freedom. Medicare Advantage typically means lower or zero premiums but network restrictions, referrals, and variable copays.
Timing matters here as much as the decision itself. Your Initial Enrollment Period is also your Medigap open enrollment window if you are 65 or older. During that six-month period, insurers cannot deny you coverage or charge more because of pre-existing conditions. Wait until later and you may be underwritten, priced higher, or turned down entirely. Medicare Advantage has its own annual enrollment windows, but your first chance to join or switch is tied to your initial Medicare enrollment.
Before you commit, write down three things: your current physicians, your current medications, and your tolerance for network rules. Then compare plans against those three criteria. Agents who work with MedicareLeads.com see this decision play out daily, and the consumers who prepare in advance close the gap between enrollment and active coverage much faster.
The Timeline From Application to Active Coverage
New beneficiaries often ask how long the whole thing takes. The honest answer is that it depends on when you apply, but a typical timeline looks like this:
- Three months before 65: Your Initial Enrollment Period opens. Apply now for the earliest possible start date.
- One to two weeks after applying: Social Security processes your request and mails your Medicare card.
- Two to four weeks after applying: You receive your card with your Part A and Part B effective dates.
- One to three months before coverage starts: You enroll in a Part D drug plan, Medicare Advantage plan, or Medigap policy.
- First day of your birthday month: Coverage begins if you enrolled on time.
If you apply after your birthday month, your Part B start date can be delayed by one to three months for each month you wait. That gap leaves you without coverage and, in some cases, without a way to fill it. Delays also trigger late enrollment penalties: 10 percent added to your Part B premium for every 12 months you were eligible but did not enroll, and 1 percent per month for Part D.
People who qualify for Medicare due to disability generally receive automatic enrollment after 24 months of Social Security disability benefits, though the timeline can shift if you are not yet receiving cash benefits. In those cases, the application through Social Security is still the trigger.
After Enrollment: Confirming Your Coverage Is Active
Submitting the application is not the finish line. Confirming that your coverage is active prevents surprises at the pharmacy counter and the doctor's office. Start by reviewing your Medicare card: it lists your Part A and Part B effective dates, your Medicare number, and your hospital and medical coverage start dates. If anything looks wrong, call Social Security immediately.
Next, confirm your supplemental coverage. If you joined a Medicare Advantage plan, you should receive a plan ID card and a welcome packet. If you bought a Medigap policy, you should receive a policy document and a card. If you enrolled in Part D, check that your pharmacy has your plan information on file. Do not assume the pharmacy will figure it out; call ahead and verify.
Finally, test your coverage with a low-stakes appointment. Schedule a routine visit or fill a prescription in the first month. If something is denied or mispriced, you have time to correct it before a serious health event. Keep a folder with your Medicare card, your supplemental cards, and any enrollment confirmations. This is also the moment to set a reminder for the Annual Enrollment Period, October 15 to December 7, so you can review your plan every year.
Agencies and independent agents who serve new beneficiaries know that a smooth application process builds trust and reduces churn. Some turn to performance-based call generation to connect with consumers at the exact moment they are ready to enroll. Platforms like PayPerCallMarketing specialize in connecting advertisers with publishers to produce high-quality phone calls, which can complement the lead products agents already use. For agents buying Medicare leads, the priority is the same as it is for consumers: a clear sequence, verified information, and coverage that starts on time.
The Medicare application process step by step for new beneficiaries comes down to five moves: apply through Social Security during your window, know whether automatic enrollment applies, choose between Original Medicare and Medicare Advantage, track your timeline, and verify your coverage once it is active. Do those in order and you avoid penalties, gaps, and last-minute scrambling. Start with your birthday month, work backward, and let each deadline guide the next action.