Illinois Medicare Advantage Plans Comparison for New Enrollees
Compare Illinois Medicare Advantage plans for new enrollees: coverage, networks, and costs. Call (510)-663-7016 for expert help.
By Atlas Reid
Turning 65 in Illinois means you have a decision to make about how you receive your Medicare benefits. You can stick with Original Medicare and add a Part D drug plan, or you can enroll in a Medicare Advantage plan that bundles hospital, medical, and often prescription drug coverage into one package. For new enrollees, the sheer number of plan options in Illinois can feel overwhelming. According to the Centers for Medicare and Medicaid Services, Illinois beneficiaries can choose from dozens of Medicare Advantage plans, each with different networks, premiums, copays, and extra benefits. This guide breaks down what you need to know to make a confident comparison, with a focus on the practical details that matter most to someone new to Medicare.
Unlike Original Medicare, which is administered by the federal government and accepted by nearly all providers nationwide, Medicare Advantage plans are offered by private insurers approved by Medicare. In Illinois, these plans vary significantly by county. A plan that works well in Cook County may not be available in Sangamon County, and the doctors you want to keep may be in-network for one plan but out-of-network for another. That is why a careful, localized comparison is essential. This article walks you through what Illinois Medicare Advantage plans typically cover, how to evaluate network rules, how cost-sharing differs between plan types, and how a local agent can simplify the process.
What Illinois Medicare Advantage Plans Typically Cover
All Medicare Advantage plans must provide at least the same coverage as Original Medicare (Part A hospital insurance and Part B medical insurance). That means hospital stays, doctor visits, outpatient care, and preventive services are included. Most plans also include prescription drug coverage (Part D), making them a convenient all-in-one option. Beyond the basics, many Illinois Medicare Advantage plans offer extra benefits that Original Medicare does not cover, such as dental, vision, hearing aids, fitness memberships, and over-the-counter drug allowances. These extras can be a major selling point, but they should not be the only factor in your decision.
Plan types vary, and each type structures coverage differently. Health Maintenance Organization (HMO) plans are the most common in Illinois. They typically require you to use a network of doctors and hospitals, and you may need a referral to see a specialist. Preferred Provider Organization (PPO) plans offer more flexibility: you can see out-of-network providers, but you will pay more. Private Fee-for-Service (PFFS) plans are less common but allow you to see any Medicare-approved provider who accepts the plan's terms. Special Needs Plans (SNPs) are for specific groups, such as people with certain chronic conditions or those eligible for both Medicare and Medicaid. Understanding these types is the first step in comparing Illinois Medicare Advantage plans.
When you review plan details, look beyond the summary of benefits. Check the formulary (drug list) if you take prescriptions, and confirm that your preferred pharmacy is in-network. Also review the plan's star rating from Medicare, which reflects quality and member satisfaction. In Illinois, plans with four or five stars often have better customer service and care coordination. Keep in mind that benefits can change each year, so a plan that looked good last year may have different copays or extra benefits this year. For new enrollees, the key is to compare plans based on your specific health needs and budget, not just the lowest premium.
In-Network vs Out-of-Network Rules to Check in Illinois
Network rules are one of the most important differences between Medicare Advantage plans in Illinois. HMO plans generally require you to receive care from a network of providers, except in emergencies or when you are traveling outside the service area (urgent care and emergency care are always covered). If you see a specialist without a referral, the plan may not pay. PPO plans allow you to see out-of-network providers, but your costs will be higher, and you may need to meet a separate deductible. Before you enroll, verify that your primary care doctor and any specialists you see regularly are in the plan's network. You can do this by checking the plan's provider directory online or calling the insurer directly.
Another factor to consider is the plan's service area. Some Illinois Medicare Advantage plans serve only certain counties or ZIP codes. If you travel frequently or split your time between Illinois and another state, you need to understand how the plan handles coverage outside its service area. HMO plans may offer limited coverage for routine care when you are away from home, while PPO plans typically provide more flexibility. Also, check whether the plan requires prior authorization for certain services, such as surgeries or advanced imaging. Prior authorization can delay care, so it is worth knowing which services require it.
For new enrollees, a common mistake is to assume that a plan accepted by a hospital is also accepted by all the doctors who practice there. In reality, each provider contracts with plans individually. Even within the same hospital system, some physicians may be in-network while others are not. That is why it is crucial to check both the hospital and the specific doctors you plan to see. If you are considering a plan that includes your preferred hospital, call the hospital's billing office and ask which Medicare Advantage plans they accept. This simple step can save you from surprise bills later.
Cost-Sharing Differences Between Plan Types
Medicare Advantage plans in Illinois use different cost-sharing structures, and understanding these differences is key to comparing plans accurately. Most plans have a monthly premium (some have a $0 premium, but you still pay your Part B premium), and you may have copays or coinsurance for services. HMO plans often have lower premiums and copays but restrict you to network providers. PPO plans tend to have higher premiums and may include deductibles, but they offer more flexibility. Some plans use a tiered copay structure for prescription drugs, with lower costs for generic drugs and higher costs for brand-name or specialty drugs.
Beyond the monthly premium, look at the maximum out-of-pocket limit. This is the most you will pay in a year for covered in-network services (and for PPO plans, there may be a separate out-of-pocket limit for out-of-network care). In 2026, the maximum out-of-pocket limit for Medicare Advantage plans is $8,850 for in-network services, but many Illinois plans set lower limits. A plan with a higher premium might actually save you money if it has a lower out-of-pocket maximum and you expect to need significant medical care. Conversely, if you are healthy and rarely see the doctor, a lower-premium plan with higher copays could be more cost-effective.
Prescription drug costs are another critical factor. Even if you do not take many medications now, your needs could change. Check each plan's formulary to see if your drugs are covered and what tier they are in. Also, review the plan's pharmacy network: using a preferred pharmacy can significantly reduce your copays. If you qualify for Extra Help (the Low-Income Subsidy), you may pay less for prescriptions. For new enrollees, it is wise to estimate your annual drug costs under each plan, not just the monthly premium. A plan with a $0 premium might have higher drug costs that outweigh the savings.
When comparing cost-sharing, do not overlook extra benefits that can offset costs. Many Illinois Medicare Advantage plans include dental, vision, and hearing coverage, which can save you hundreds of dollars per year if you use those services. Some plans offer fitness memberships (such as SilverSneakers) and over-the-counter allowances. These extras can make a plan with a slightly higher premium a better value overall. However, be realistic about which benefits you will actually use. If you already have dental coverage through a retiree plan or the VA, for example, you may not need a plan that includes dental.
How to Use a Local Agent to Compare Illinois Plans
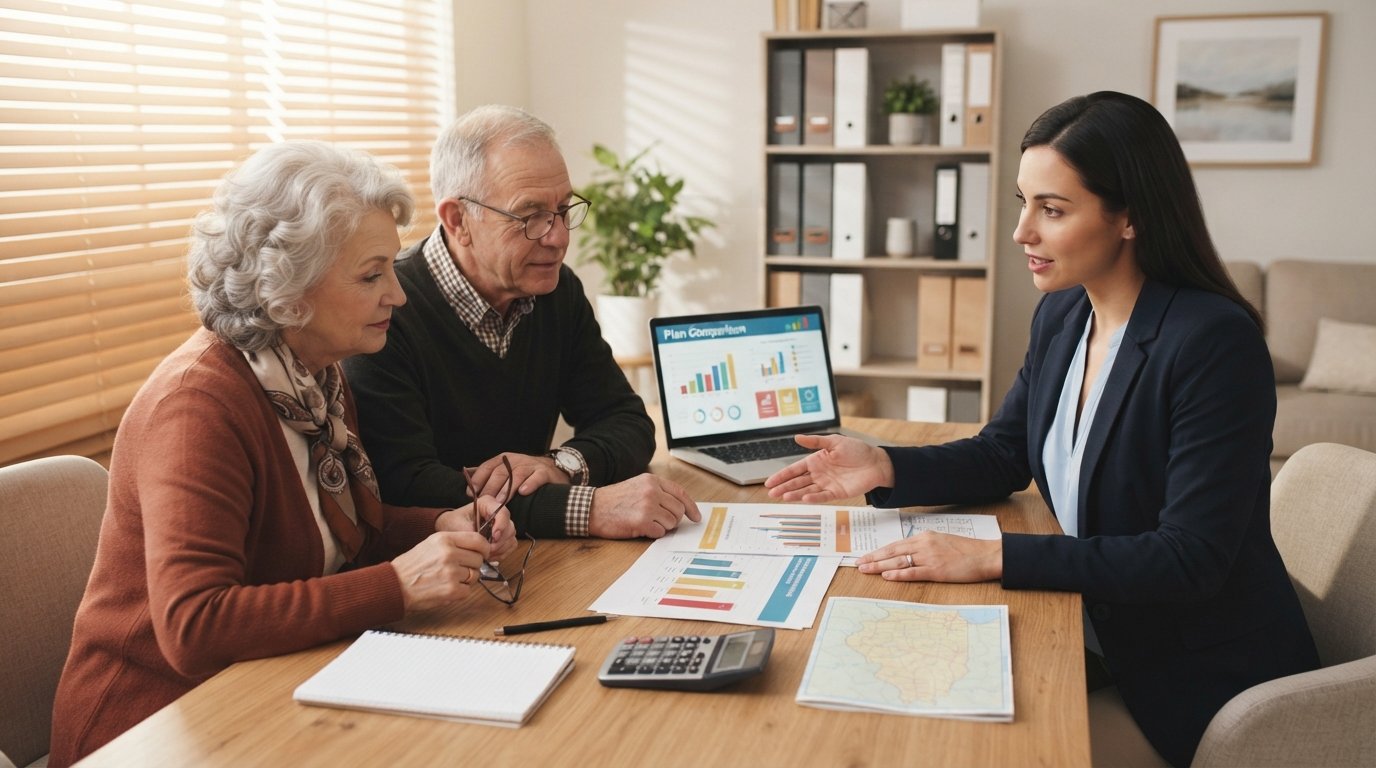
Comparing Illinois Medicare Advantage plans on your own can be time-consuming and confusing. That is where a local, licensed insurance agent can help. Agents who specialize in Medicare have access to plan comparison tools that show all the options available in your ZIP code, including details on premiums, copays, networks, and drug formularies. They can help you narrow down the choices based on your doctors, medications, and budget. More importantly, a local agent understands the nuances of the Illinois market, such as which plans have strong provider networks in your area and which ones have a history of poor customer service.
When you work with an agent, be prepared to share your list of doctors and prescriptions. The agent can then run a comparison and identify plans that cover your needs. They can also explain the differences between HMO and PPO plans, and help you understand the trade-offs. A good agent will not push you toward a particular plan; instead, they will present the options and let you decide. They can also help you enroll and ensure your application is processed correctly. If you are new to Medicare, an agent can also explain how Medicare Advantage interacts with other coverage, such as employer retiree plans or Medicaid.
If you are an agent looking to help new enrollees in Illinois, having a reliable source of qualified leads is essential. MedicareLeads.com provides exclusive and shared Medicare leads, inbound calls, and live transfers to licensed agents. Their platform allows you to target consumers by state or ZIP code, so you can focus on Illinois residents who are actively seeking Medicare Advantage plans. To learn more about how lead quality impacts your sales, read our comparison of Medicare Advantage leads vs supplement conversions. For agents who also serve other markets, such as legal professionals, AttorneyLeads offers a similar model for legal lead generation.
For new enrollees, the key is to start early. The Initial Enrollment Period (IEP) begins three months before your 65th birthday month and ends three months after. If you miss it, you may face penalties or gaps in coverage. During the IEP, you can enroll in a Medicare Advantage plan without answering health questions. If you have a chronic condition, you may qualify for a Special Needs Plan. And if you are low-income, you may qualify for a Dual Eligible Special Needs Plan (D-SNP) that coordinates Medicare and Medicaid benefits. A local agent can help you determine which enrollment period applies to you and which plans you are eligible for.
In summary, comparing Illinois Medicare Advantage plans for new enrollees requires attention to plan type, network rules, cost-sharing, and extra benefits. Do not rely solely on premiums or marketing materials. Use the resources available, including Medicare's Plan Finder tool and licensed agents, to make an informed decision. And remember that you can change plans during the annual Open Enrollment Period (October 15 to December 7) if your needs change. With careful research and the right help, you can find a plan that keeps you healthy and protects your finances.
For personalized assistance with your Illinois Medicare Advantage comparison, call (510)-663-7016 to speak with a licensed agent. They can help you review your options and enroll in a plan that fits your needs.