Dental Insurance With No Waiting Period: Agent Guide
Dental insurance with no waiting period can start paying for crowns and fillings on day one. Call (510)-663-7016 for agent guidance.
By Dorian Vale
When a client calls you in pain and needs a crown or root canal next week, a dental plan with a six to twelve month waiting period is useless. That urgency is exactly why dental insurance with no waiting period has become one of the most searched plan features among seniors, self-employed workers, and families who need coverage that works immediately. For licensed agents, the opportunity is significant: prospects who understand the value of immediate coverage convert faster and stay longer, because they bought the plan for a real need rather than a vague intention.
This guide breaks down how no waiting period dental plans actually work, which products genuinely skip the waiting periods, how to position them ethically, and how to build a steady pipeline of qualified dental and Medicare prospects. Whether you sell individual dental policies, bundle dental with Medicare Advantage, or simply want to answer client questions with confidence, the details below will help you separate real immediate coverage from marketing hype.
What a No Waiting Period Dental Plan Actually Means
A standard individual dental insurance policy usually splits benefits into three tiers: preventive care (cleanings, exams, X-rays), basic restorative care (fillings, extractions), and major services (crowns, bridges, dentures, root canals). Most carriers impose waiting periods of six to twelve months before basic and major services become payable, sometimes with a shorter window for preventive care. The waiting period exists because carriers want premium dollars to accumulate before they pay out large claims.
A dental insurance with no waiting period plan removes or drastically shortens those windows. Preventive care is typically covered on day one in almost every policy, but true no waiting period plans also make basic and major services eligible immediately, usually in exchange for a higher monthly premium, a lower annual maximum, or both. Some products use a graded schedule instead, paying a percentage of major services that increases each year, which is not the same as a genuine no waiting period benefit.
It helps to separate the categories clearly, because prospects often conflate them:
- True no waiting period plans: preventive, basic, and major services are all eligible from the effective date, subject to annual maximums and deductibles.
- Preventive-only immediate coverage: cleanings and exams are covered right away, but fillings and crowns still require a waiting period.
- Graded benefit plans: major services are covered immediately but at a reduced percentage that rises over two to three years.
- Discount dental plans: not insurance at all, but a negotiated fee schedule that delivers savings immediately with no claims process.
Knowing which bucket a plan falls into protects you from compliance problems and protects your client from surprise bills. When you quote a no waiting period dental plan, read the certificate of coverage and confirm exactly which service categories are eligible on day one. If the carrier only waives the waiting period for preventive care, say so plainly. Clients remember being misled far longer than they remember a slightly higher premium.
Who Benefits Most From Immediate Dental Coverage
The demand for dental insurance with no waiting period is concentrated in a few predictable groups, and recognizing them helps you target your marketing and shape your pitch. Seniors aging into Medicare are a major segment: original Medicare does not cover routine dental care, and many Medicare Advantage plans offer only limited dental benefits, so a standalone dental policy fills a real gap. Seniors who postponed care during a period without coverage often have a backlog of needed work, which makes immediate eligibility the deciding factor.
Self-employed workers, gig economy earners, and small business owners without employer-sponsored dental are another core audience. They typically shop mid-year after a dental emergency or a change in employment, and they cannot wait six months for a crown to become payable. Families who lose group coverage, employees who miss an open enrollment window, and people preparing for a known procedure such as an implant or denture also search specifically for plans that start paying right away.
For agents, this creates a useful segmentation framework. Ask three questions on every dental conversation: does the prospect have an immediate need or a preventive-care need, do they have other coverage that might coordinate, and what is their budget tolerance for a higher premium in exchange for immediate eligibility. The answers point directly to the right product category and prevent wasted quotes.
How No Waiting Period Plans Are Priced and Structured
Immediate coverage is not free coverage, and understanding the trade-offs lets you set honest expectations. Carriers that eliminate waiting periods typically manage risk through four levers: higher monthly premiums, lower annual maximums (often $1,000 to $1,500 rather than $2,000 or more), higher deductibles for basic and major services, and coinsurance that requires the member to pay a meaningful share of each procedure. Some plans also exclude certain high-cost services for a period even when the general waiting period is waived.
A typical structure for a no waiting period individual dental plan looks like this: preventive care at 100 percent with no deductible, basic services at 70 to 80 percent after a modest deductible, and major services at 50 percent after a higher deductible, all effective on day one. The member pays a premium of roughly $40 to $70 per month depending on age and region, and the plan caps total annual payments at the annual maximum. Compare that to a waiting period plan with a $25 premium and a twelve month wait on major services, and the trade-off becomes clear: the immediate plan costs more but can pay for itself with a single crown.
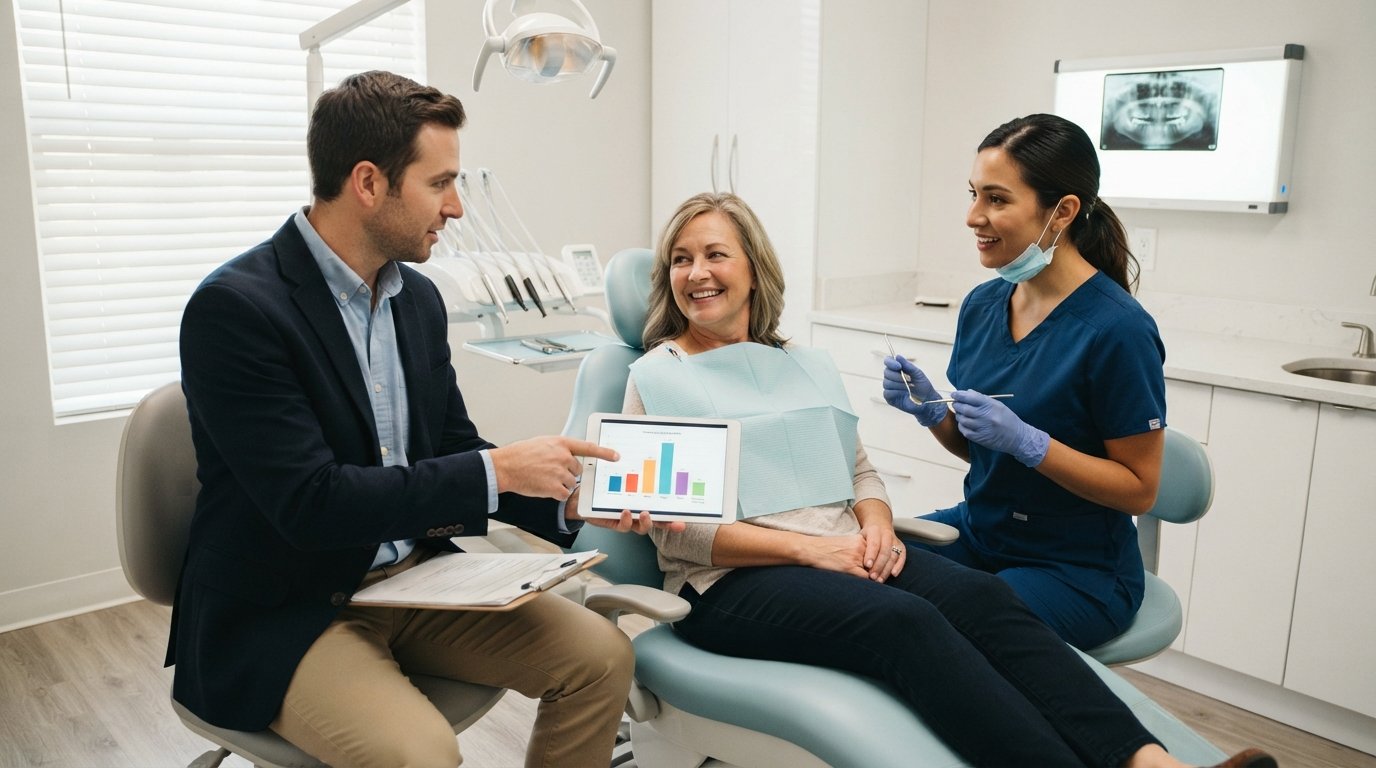
Run the math with your client rather than for them. A crown often costs $1,200 to $1,800 without insurance; a no waiting period plan at 50 percent coinsurance after a $100 deductible might pay $550 to $850 toward that crown, which can exceed a full year of premiums. That comparison is the single most persuasive tool you have, and it is honest because it is grounded in the client's actual situation.
Medicare, Medicare Advantage, and Dental Coverage Gaps
Original Medicare (Part A and Part B) does not cover routine dental care, cleanings, fillings, or dentures, and it covers dental services needed for certain medical procedures only in narrow circumstances. Many Medicare Advantage plans advertise dental benefits, but the depth varies enormously: some offer only preventive cleanings, others include annual maximums of $1,000 or more, and a few include no waiting periods for basic services. Medicare Supplement plans do not add dental coverage at all, which is why standalone dental policies remain a common add-on sale.
This is where agent positioning matters. When you discuss Medicare Advantage enrollment with a client who has pending dental needs, verify the plan's dental benefit details, including waiting periods, annual maximums, and network restrictions, before promising anything. If the Advantage plan's dental benefit is thin, a standalone no waiting period dental policy can fill the gap, and bundling the conversation around total healthcare costs builds trust that carries into future enrollment seasons.
For agents building a Medicare-focused book, dental is a natural door opener and retention tool. A client who buys a dental policy from you in March is far more likely to call you during the Annual Enrollment Period in the fall. If you want a deeper walkthrough of plan structures and carrier options, our guide to dental insurance plans with no waiting period covers the plan-level details you can share with clients.
Compliance and Ethical Selling for Immediate Dental Plans
Dental insurance marketing is regulated, and the phrase "no waiting period" is a claim that must be accurate for the specific plan you are presenting. Several states and the National Association of Insurance Commissioners have scrutinized dental marketing for misleading language, particularly around annual maximums, network limitations, and pre-existing condition exclusions. Present the certificate of coverage, not the sales brochure, when confirming what is covered on day one.
Follow a short compliance checklist on every dental presentation. Confirm the plan's effective date rules (most carriers require enrollment by a certain day of the month for a first-of-next-month start), disclose any pre-existing condition limitations, explain the annual maximum and deductible clearly, and state whether the plan uses a network and what happens out of network. If you generate leads through digital channels, keep your landing page claims consistent with the carrier-approved materials, because regulators increasingly review the full funnel, not just the enrollment call.
Ethical selling also means disqualifying the wrong prospect. If a client needs a $3,000 implant next month and the plan has a $1,500 annual maximum, the plan will not cover the full procedure, and telling them otherwise creates a complaint and a chargeback. Set expectations at the point of sale: the plan reduces cost, it does not eliminate it, and the annual maximum is a hard ceiling.
Finding Qualified Dental and Medicare Prospects
Lead quality determines whether no waiting period dental products are profitable for your agency. The best prospects either have an immediate need or are actively comparing coverage, and they respond to specific messaging rather than generic "affordable dental insurance" ads. Build your campaigns around the trigger events: losing employer coverage, a dentist recommending a crown or bridge, turning 65, or enrolling in a Medicare Advantage plan with limited dental benefits.
On the paid side, search and social campaigns targeting phrases like "dental insurance no waiting period" and "immediate dental coverage" attract high-intent shoppers, but competition is heavy and cost per lead can climb quickly. On the organic side, educational content and local pages build durable inbound traffic. For agents who want to skip the cold-start phase and buy validated inquiries, platforms such as PingPost.Exchange provide real-time lead distribution where buyers can bid on consumer inquiries as they arrive, which pairs well with dental and Medicare campaigns that need fast follow-up.
Speed to contact is the single biggest lever on lead conversion. Consumers shopping for immediate dental coverage often enroll within 48 hours, and the first agent to reach them with a clear, accurate quote usually wins the sale. Set up automatic callbacks, text follow-up, and a same-day quote workflow so no lead sits overnight.
A Step-by-Step Client Conversation Framework
Use a consistent four-step conversation to move a prospect from interest to enrollment without pressure. First, diagnose the need: ask what dental work is pending, when they last saw a dentist, and whether they have other coverage. Second, match the product: true no waiting period plan for immediate needs, preventive-focused plan for budget-conscious clients, or a discount plan if insurance is unaffordable. Third, run the numbers together: premium plus deductible plus coinsurance versus the cash cost of the expected procedures. Fourth, close on the effective date: confirm the enrollment deadline for the earliest possible start and set expectations about ID cards and provider networks.
Scripted discovery questions keep the conversation efficient and documented. A simple sequence works well: "What dental treatment has your dentist recommended, and is it scheduled?" then "Do you currently have any dental coverage, including through an employer or Medicare Advantage plan?" then "If a plan could cover part of that treatment next month, what monthly budget feels comfortable?" The answers tell you whether to lead with a no waiting period plan, a graded benefit plan, or a referral to a dentist for a treatment plan first.
Marketing No Waiting Period Dental Plans to the Right Audience
Effective marketing for immediate dental coverage is specific. Generic ads blend into a crowded field, while ads that name the trigger event ("Need a crown? Coverage can start next month") convert at a fraction of the cost. Build separate landing pages for seniors on Medicare, self-employed workers, and families losing group coverage, and keep the carrier-approved compliance language consistent across each page.
Email and text follow-up sequences should address the top three objections: cost, network, and whether the waiting period is truly waived. A three-touch sequence over five days, with a clear quote and a link to the certificate of coverage, converts well because it respects the prospect's urgency. Track cost per enrollment, not just cost per lead, and cut any source that produces shoppers who cannot pass underwriting or who live outside the plan's service area.
Finally, remember that dental is a relationship product. A client who enrolls for an urgent crown this year will need cleanings next year, and the agent who handled the urgent situation honestly earns the renewal and the referral. That compounding effect is why no waiting period dental plans deserve a permanent place in your product mix, not just a seasonal campaign. For agents ready to scale, combining educational content, fast lead follow-up, and accurate compliance language creates a durable pipeline that serves clients well and grows your book year after year.