Dental Insurance Plans No Waiting Period: A Guide for 2026
Get immediate dental coverage with dental insurance plans no waiting period. Call (510)-663-7016 to find the right plan for your needs.
By Lyra Vale
Imagine needing a root canal or a crown and discovering that your dental insurance will not cover it for six to twelve months. That is the reality for many people who buy individual dental plans without checking the fine print. Waiting periods are common in dental insurance, but they are not unavoidable. With dental insurance plans no waiting period, you can get coverage for immediate dental needs and avoid surprise bills. This guide explains how these plans work, what to look for, and how to choose the right one for your situation.
What Are Dental Insurance Plans with No Waiting Period?
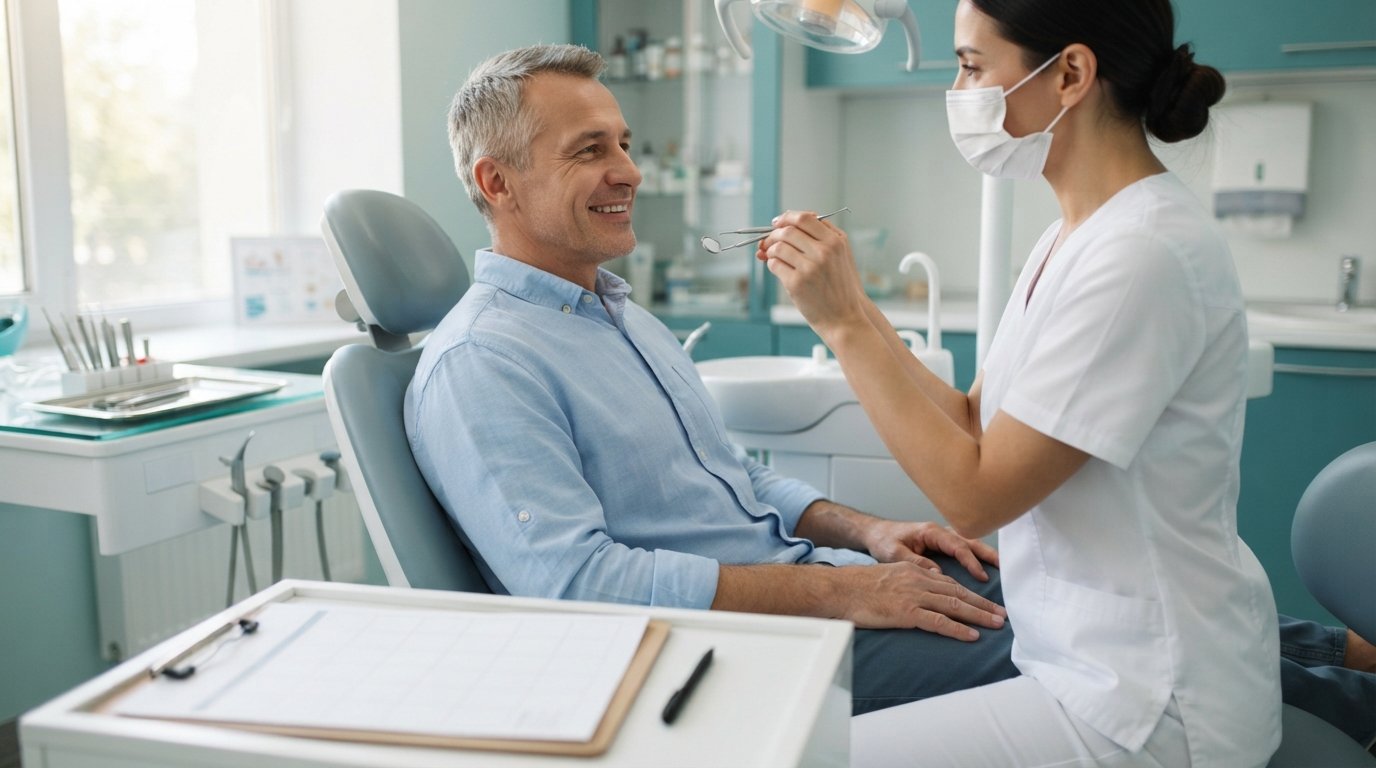
Dental insurance plans with no waiting period are policies that allow you to use your benefits immediately upon enrollment. Unlike traditional dental insurance, which often imposes waiting periods of six to twelve months for major services like crowns, bridges, or root canals, these plans skip that delay. That means you can schedule that filling, extraction, or even denture work without worrying about whether your plan will pay.
Waiting periods exist because insurers want to prevent people from buying coverage only when they need expensive treatment. However, many insurers now offer plans without waiting periods to attract customers who need immediate care. These plans may have higher premiums or different cost-sharing structures, but they provide peace of mind for those with urgent dental issues.
It is important to distinguish between no waiting period plans and discount dental plans. Discount plans are not insurance; they offer reduced rates from a network of providers for an annual fee. No waiting period insurance plans are actual insurance policies that pay benefits according to the plan's terms. Always verify that you are buying insurance, not a discount plan, if you need coverage that meets your state's insurance requirements.
How No Waiting Period Dental Insurance Works
When you enroll in a dental insurance plan with no waiting period, your coverage typically begins on the effective date of the policy. There is no delay for preventive care, basic services, or major services. However, the plan may still have annual maximums, deductibles, and coinsurance that affect how much you pay out of pocket.
For example, a plan might cover preventive care at 100% with no deductible, basic services at 80% after a $50 deductible, and major services at 50% after the same deductible. The annual maximum might be $1,000 or $2,000. Even with no waiting period, you are still responsible for your share of the costs. Understanding these details is crucial to avoid surprises.
Some plans also have graduated coverage, where the insurer pays a higher percentage after you have been enrolled for a certain period, even if there is no formal waiting period. For instance, major services might be covered at 30% in the first year and 50% in the second year. Always read the plan details carefully to understand how benefits are structured.
Types of Dental Insurance Plans with No Waiting Period
There are several types of dental insurance plans that may offer no waiting periods. The most common are PPO (Preferred Provider Organization) plans, HMO (Health Maintenance Organization) plans, and indemnity plans. Each has its own network and cost structure.
- PPO plans: These plans have a network of dentists but allow you to see out-of-network providers for a higher cost. No waiting period PPO plans are widely available and offer flexibility.
- HMO plans: These plans require you to use in-network dentists and often have lower premiums. They may offer no waiting periods but have limited provider choices.
- Indemnity plans: These plans allow you to see any dentist and submit claims for reimbursement. They may have no waiting periods but often have higher premiums and annual maximums.
Additionally, some plans are designed specifically for individuals and families who need immediate coverage, such as those who have lost employer-sponsored dental coverage or who are self-employed. These plans often emphasize no waiting periods as a key selling point.
When comparing plans, consider not only the waiting period but also the network of dentists, the annual maximum, the deductible, and the coinsurance. A plan with no waiting period but a low annual maximum may not be sufficient if you need extensive dental work.
Benefits of No Waiting Period Dental Insurance
The most obvious benefit is immediate access to care. If you have a dental emergency or have been putting off necessary treatment, a no waiting period plan can save you from paying entirely out of pocket. This is especially valuable for people who have neglected their dental health due to cost or lack of insurance.
Another benefit is predictability. With a no waiting period plan, you know that your coverage is active right away, so you can plan treatments without worrying about when your benefits will kick in. This can be particularly important for families with children who may need orthodontic evaluations or other time-sensitive care.
Additionally, no waiting period plans can be cost-effective if you anticipate needing major dental work within the first year. For example, if you know you need a crown that costs $1,200, a plan with a $1,000 annual maximum and no waiting period could cover a significant portion, even after accounting for premiums and deductibles.
However, it is essential to weigh the benefits against the costs. No waiting period plans often have higher premiums than plans with waiting periods. If you do not expect to need major dental work soon, a plan with a waiting period might be more economical.
How to Choose the Right No Waiting Period Dental Plan
Choosing the right plan requires careful consideration of your dental needs, budget, and preferences. Start by assessing your current dental health and any anticipated treatments. If you need immediate care, prioritize plans with no waiting periods for the services you need.
Next, compare the costs: premiums, deductibles, coinsurance, and annual maximums. A plan with a low premium but high out-of-pocket costs may not be the best value if you need extensive work. Use a cost estimator or ask the insurer for a breakdown of costs for specific procedures.
Check the network of dentists. If you have a preferred dentist, make sure they are in the plan's network. Otherwise, you may face higher costs or have to switch providers. Also, consider the plan's reputation and customer service. Look for reviews and ratings from other members.
Finally, read the plan documents carefully. Understand what is covered, what is excluded, and any limitations. Some plans may have no waiting period for preventive care but still impose waiting periods for major services. Ensure that the plan truly has no waiting period for the services you need.
Common Exclusions and Limitations
Even no waiting period plans have exclusions and limitations. For example, orthodontic treatment is often excluded or has a separate waiting period. Cosmetic procedures like teeth whitening are typically not covered. Pre-existing conditions may also be excluded, although some plans cover them after a certain period.
Annual maximums are a significant limitation. Most dental insurance plans have an annual maximum of $1,000 to $2,000. If you need extensive work, you may exceed this limit and be responsible for the remaining costs. Some plans offer higher maximums for higher premiums.
Additionally, some plans may require you to use in-network dentists or obtain pre-authorization for certain procedures. Failure to follow these rules could result in reduced benefits or denied claims. Always review the plan's provider directory and pre-authorization requirements.
Tips for Maximizing Your No Waiting Period Dental Insurance
To get the most out of your plan, schedule a preventive visit as soon as your coverage begins. Preventive care is often covered at 100% and can help you avoid more costly treatments later. Your dentist can also provide a treatment plan that outlines any necessary work, which you can then coordinate with your insurance benefits.
If you need major work, ask your dentist to submit a pre-treatment estimate to the insurance company. This will give you an idea of how much the plan will pay and how much you will owe. It also helps you plan financially.
Keep track of your annual maximum and use it wisely. If you have remaining benefits near the end of the year, consider scheduling any needed treatments before the maximum resets. Some plans allow you to roll over unused benefits, but that is rare.
Finally, stay informed about your plan's network and any changes to benefits. Insurance plans can change their networks and coverage from year to year, so review your plan documents annually.
No Waiting Period Dental Insurance for Medicare Beneficiaries
Medicare does not typically cover routine dental care, so many beneficiaries look for standalone dental insurance plans. No waiting period plans can be particularly attractive for Medicare beneficiaries who need immediate dental work. When shopping for these plans, consider the same factors as any other dental plan: premiums, coverage, network, and annual maximums.
Some Medicare Advantage plans offer dental benefits, but these often have waiting periods or limited coverage. If you need comprehensive dental care without waiting, a standalone no waiting period dental insurance plan may be a better option. Be sure to compare plans and read the fine print.
For insurance agents, understanding the nuances of dental insurance plans no waiting period is essential to serve clients who may be transitioning from employer coverage or who have urgent dental needs. Offering guidance on these plans can be a valuable service that builds trust and loyalty.
If you are an agent looking to expand your client base, consider partnering with a lead generation platform that specializes in insurance leads. For example, AttorneyLeads provides exclusive legal leads, but for Medicare and health insurance leads, MedicareLeads.com offers a range of solutions. Our guide on dental insurance plans with no waiting period provides additional insights for agents and consumers alike.
Frequently Asked Questions
Are no waiting period dental plans more expensive?
They can be. Because the insurer assumes more risk by covering services immediately, premiums may be higher than plans with waiting periods. However, the difference varies by plan and insurer. It is worth comparing quotes to see if the extra cost is justified by your anticipated dental needs.
Can I get a no waiting period plan if I have pre-existing dental conditions?
Some plans may exclude pre-existing conditions or impose a waiting period for them. Others may cover them immediately but charge a higher premium. You will need to disclose your dental history when applying and read the plan's exclusions carefully.
Do no waiting period plans cover orthodontics?
Most dental insurance plans do not cover orthodontics for adults, or they impose a waiting period of 12 to 24 months. Some plans offer orthodontic coverage as an optional rider. If you need orthodontic work, look for a plan that specifically includes it with no waiting period.
How soon can I use my benefits after enrolling?
Typically, coverage begins on the effective date of the policy, which is usually the first of the month after enrollment. However, some plans may have a short delay for certain services. Check the plan details for the exact effective date and any conditions.
What is the difference between a no waiting period plan and a discount dental plan?
A no waiting period insurance plan is a true insurance policy that pays benefits according to its terms. A discount dental plan is not insurance; it offers reduced rates from a network of providers for an annual fee. Discount plans may not meet the requirements for insurance coverage, so choose based on your needs.
Dental insurance plans no waiting period offer a practical solution for individuals and families who need immediate dental care without the delay of traditional waiting periods. By understanding how these plans work and comparing options carefully, you can find coverage that meets your needs and budget. Whether you are an insurance agent helping clients navigate their options or a consumer seeking care, the key is to read the fine print, compare costs, and choose a plan that provides the coverage you need when you need it.